







Sending money should be simple. But before you hit send, you need the right bank details.
For a UK transfer, that usually means the recipient’s name, sort code and account number. Sending international transfers can require a few more details, such as an IBAN, BIC or SWIFT code, depending on the country and payment route.
Get the details right, and your payment can move smoothly. Get them wrong, and you could face delays, rejected payments, or extra costs.
In this guide, we’ll explain the bank details you need for UK and international transfers, what IBAN, BIC, and SWIFT codes mean, and how WorldFirst can help you move money globally.
Key Takeaways
- Domestic and international transfers need different details
UK transfers usually need the recipient’s name, sort code and account number. International transfers may also require an IBAN, BIC or SWIFT code, destination country and payment currency. - Accuracy matters because mistakes can delay or block payments
A small mistake can delay, reject or misdirect a payment. Double-check the recipient’s name, account details and bank identifiers before confirming. - Security checks are now a normal part of sending money
Banks often require two-factor authentication, verification codes and fraud checks, which can help protect your payment when you send money online, helping reduce the risk of scams and unauthorised payments. - Traditional SWIFT transfers can be slow, expensive, and unpredictable
Traditional SWIFT payments can involve intermediary fees and longer processing times. Where available, local payment networks can offer a faster, more efficient route. - A World Account is positioned as a smarter option for faster and cheaper global transfers
With a World Account, you can receive payments in 20+ currencies, send payments in 100+ currencies, and use local account details and payment routes where available.
What information do you need to transfer money within the UK?
If you’re making a UK bank transfer through online banking or at a bank branch, you’ll usually need your payee’s:
- Full name
- 6-digit sort code
- 8-digit account number
You may also need the payee’s address or a payment reference, depending on the type of payment. If you’re receiving money, you’ll generally need to provide the same bank details to the sender.
Add a payment reference if needed, so your recipient knows what the payment is for. You can also set up standing orders or schedule payments through many banks, making it easier to manage regular transfers. Transfer times vary depending on the payment method, bank, and processing times.
What security details do you need to provide for a bank transfer?
To help prevent fraud, UK banks have introduced security checks such as two-factor authentication (2FA) to ensure that scammers aren’t using your bank account details fraudulently.
Once 2FA is set up, you’ll need to answer your own security questions to set up a standing order or make an online bank transfer. If you’re asked for a verification code, you’ll receive this either on your mobile or to your email address.
You’ll then need to confirm that you understand the fraud risk and that you can’t retract your payment once it’s been sent.
What details do you need to make an international bank transfer from the UK?
In order to make a cross-border bank transfer, you’ll need the following details:
- Your name or your company’s name
- The International Bank Account Number (IBAN) of the account you want to credit
- The Bank Identifier Code (BIC) of your payee’s bank, also known as a SWIFT code
You’ll also usually need to confirm the currency you want the payment to be sent in, as well as the country you’re sending it to. Additionally, you might also need to confirm the receiving bank name is correct to ensure funds don’t get sent into the wrong account.
If you want to receive international payments, then you’ll need to supply these same details to your payer.
The problem with relying on SWIFT transfers
The Society for Worldwide Interbank Financial Telecommunication (SWIFT) network is a convenient, internationally accepted way of transferring money across the globe. However, it’s important to be aware that using SWIFT does come with a number of drawbacks.
- SWIFT transfers tend to involve high costs, including bank charges, intermediary fees, and exchange-rate markups.
- Each bank sets its own fees, which means you often won’t know the true cost until after the transfer settles. Intermediary and banking charges can reduce the amount received, depending on the payment route and banks involved.
- Traditional SWIFT payments can take several business days to settle, depending on the payment route and destination. This can leave funds in transit for longer, tying up your cash flow and delaying payments to suppliers or receipt of funds.
If you’re looking for an alternative to SWIFT, our guide, What’s the best way to send money overseas? 7 top options for businesses, explores the different ways you can make international payments.
How WorldFirst’s World Account helps you send and receive same-day payments
Sending money overseas doesn’t have to mean dealing with multiple banks, complicated payment routes, and unpredictable arrival times.
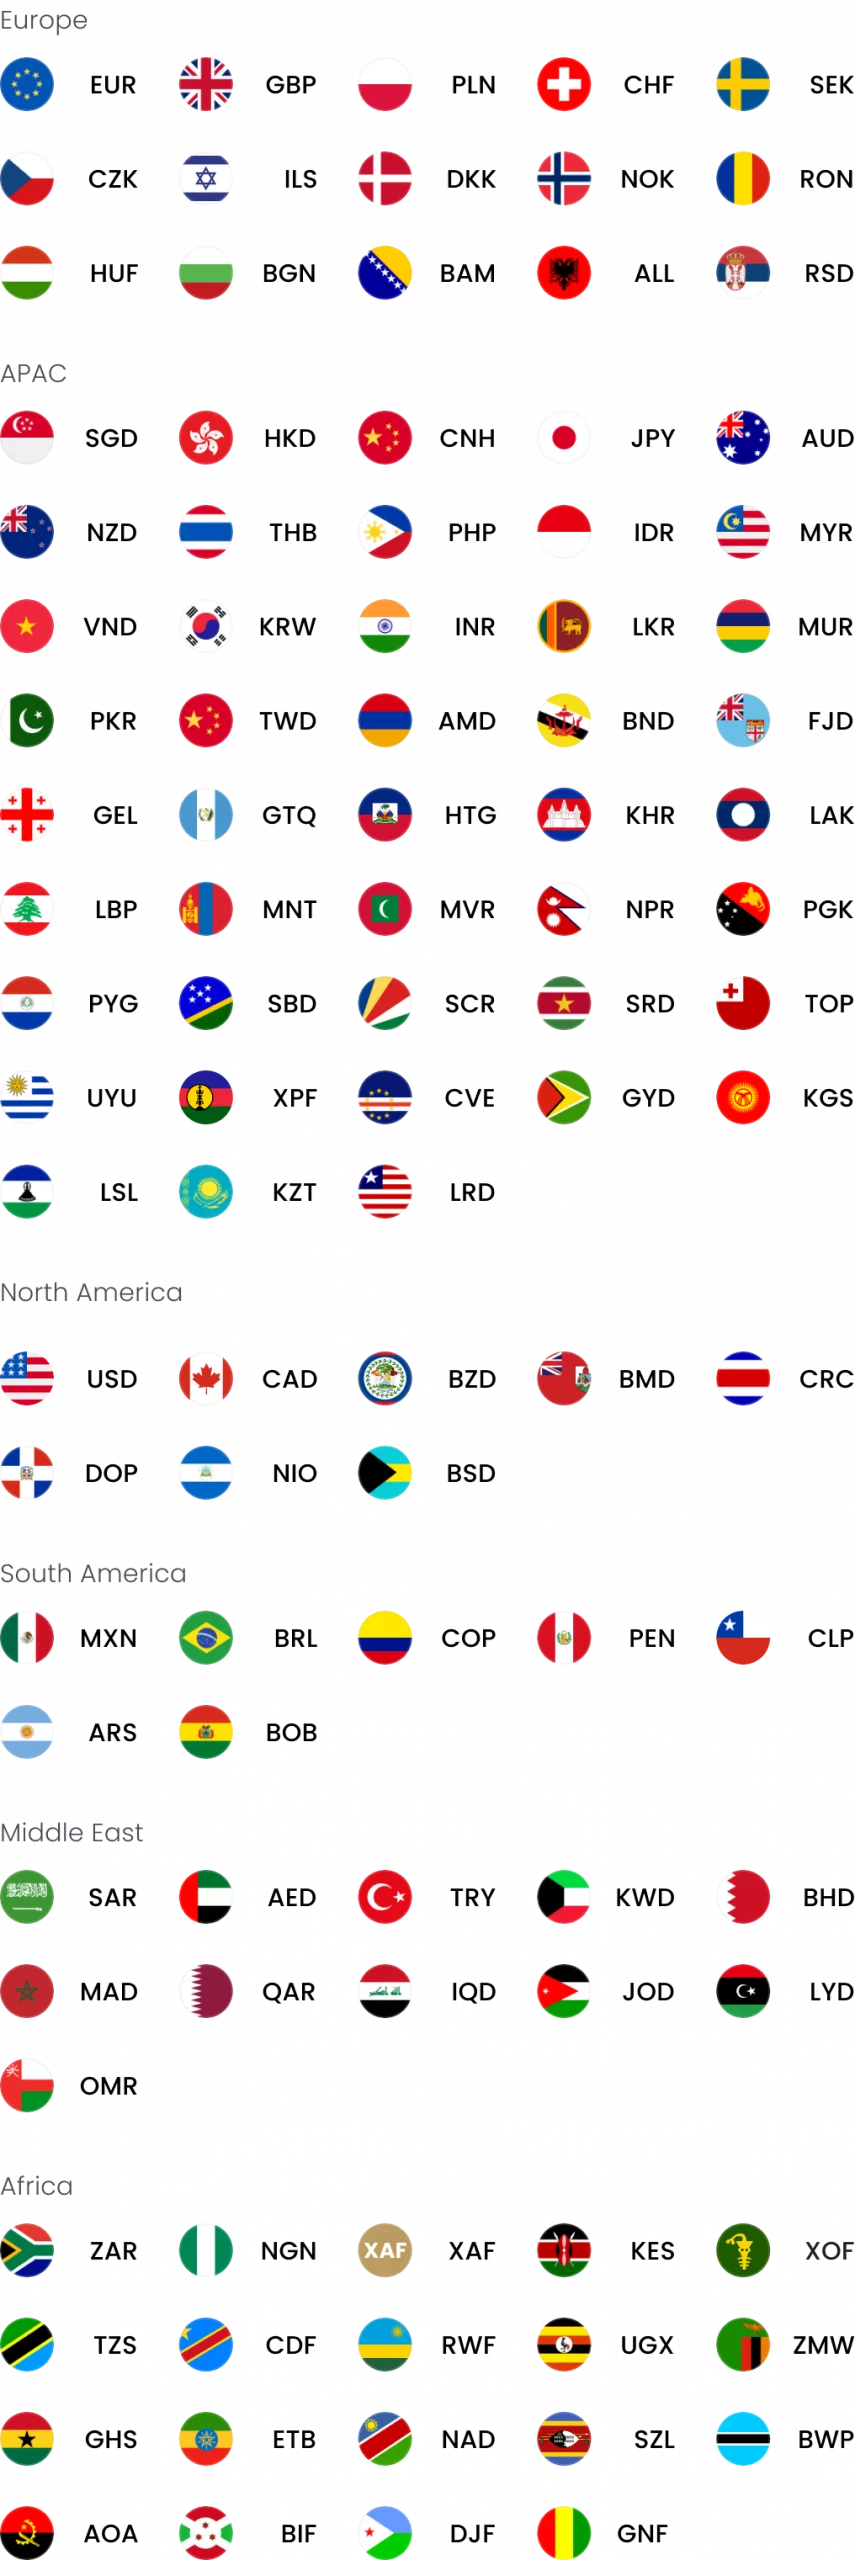
WorldFirst’s World Account gives businesses one place to send, receive, hold, and manage money across currencies. It supports receiving payments in 20+ currencies and sending payments in 100+ currencies.
Since 2004, we’ve helped more than 1.5 million businesses send over US$500 billion around the world. With local account details and payment networks, the World Account helps businesses move money globally while keeping more control over their international payments.
It’s free to open, with no ongoing account fees, and you can create local account details in supported currencies to send and receive payments more like a local.
Here’s how a World Account can help you manage international payments.
Pay like a local in 20+ currencies and avoid expensive SWIFT fees
With WorldFirst, you can pay like a local in 20+ currencies, resulting in more affordable, faster payments.
Within your World Account, you can create multiple sets of domestic bank details entirely for free, including your own unique BICs, account numbers and sort codes.
By using these local details, your international payments can bypass the SWIFT network entirely, instead being processed through domestic networks like CHAPS, the Faster Payments service or SEPA in Europe. Your funds are treated as domestic transactions rather than international ones
This way, you can avoid expensive SWIFT fees and any additional currency exchange charges from intermediary banks. We’ll always send your payment through the fastest route possible, which is why 95% of WorldFirst payments land on the same day and 90% settle by the next business day.
It’s also completely free to send payments to other World Accounts, which is especially useful if you’re primarily making domestic transactions in GBP, or sending to overseas suppliers who already have an account with WorldFirst.
If you’re planning a large international payment, What’s the best way to transfer large sums of money internationally? explores the key options and what to consider before you send.
Convert currencies at affordable rates when sending payments overseas
The cost of an international transfer varies by provider, payment route, currency, and exchange rate. For businesses that make frequent international payments, these costs can add up quickly.
In contrast, WorldFirst helps you save on currency conversion costs by offering competitive and transparent pricing. For instance, we add a maximum conversion fee of 0.5% to the mid-market exchange rate for major currencies like GBP, USD, and EUR. For all non-major currencies, our FX fee is capped at 0.75%.
To protect against market volatility and fluctuations in the underlying exchange rate, you can also take advantage of advanced FX tools like forward contracts. This lets you convert currency at a set exchange rate in the future, and with WorldFirst’s currency forwards, you can lock in rates for up to 24 months.
Another option is to set up rate alerts to get notified once an exchange rate hits your desired level. Alternatively, you could place a firm order, which automatically executes the currency conversion on your behalf once that rate becomes available.
When exchange rates move, your costs can move with them. Foreign exchange risk management: How to make international business more affordable shows you how to plan ahead and keep FX risk in check.
Use advanced security features to keep your funds safe
WorldFirst uses advanced security measures to help protect your account and payments.
We offer advanced anti-fraud protections like two-factor authentication (2FA) and 256-bit encryption to make your World Account more secure. Having 2FA means you’ll be asked to enter an extra code whenever you log into your account, create a new payee, or make a payment.
We also support real-time fraud monitoring and 3D Secure (3DS) card payments so that we can safeguard you against unauthorised access and scams.
You can create up to 25 virtual World Cards in your World Account, subject to eligibility and applicable terms. Simply create a new debit card, use those details, and then immediately delete your card once you’ve made your payment so the card can’t be reused and funds compromised.
Sending money overseas? A few simple checks can go a long way. International money transfer security tips and best practices explain how to keep your international payments secure.
Open a World Account to make fast, cost-effective transfers worldwide
The right bank details help your payment reach the right place. But when you’re sending money overseas regularly, there’s more to consider, from payment routes and FX costs to speed and security.
A World Account brings your international payments into one place, so you can receive, hold, convert and send money across currencies using local account details and payment routes where available.
With a World Account, you can:
- Receive local account details for 20+ currencies and access local payment networks.
- Avoid expensive SWIFT fees and benefit from low currency conversion costs.
- Keep funds secure with advanced security features like 2FA and 3DS card payments.
- Create up to 25 virtual World Cards, each with unique payment details.
Your business moves fast. Your money should too. Open a World Account for free and start moving money globally.
FAQs
1. What details do I need to make an international bank transfer?
You’ll usually need the recipient’s name, IBAN or account number, BIC or SWIFT code, bank name, destination country, and payment currency. Depending on the payment route, you may also need the recipient’s address or a payment reference.
2. How long does an international bank transfer take?
The time depends on the payment route, currency, destination, and banks involved. Traditional international transfers can take several business days, while local payment networks can help payments arrive faster. With WorldFirst, 80% of payments arrive on the same day, and 90% arrive by the next business day.
3. Can I send an international payment without using SWIFT?
It depends on the currency, destination, and payment route. Some international payments can be processed through local payment networks instead of SWIFT. WorldFirst uses local payment routes where available, helping eligible payments move faster and reducing reliance on intermediary banks.