










Malaysia’s Sales and Service Tax (SST) is key to running successful operations, managing costs, and avoiding penalties. Knowing how SST affects day-to-day business activities can make it easier for SMEs to plan pricing, cash flow, and compliance.
In this guide, we’ll break down everything you need to know about SST in Malaysia, from the requirements to who’s eligible and what’s taxable and exempt.
Key Takeaways
- SST in Malaysia has two parts: Sales Tax on taxable manufactured and imported goods, and Service Tax on prescribed taxable services.
- An SST number is the registration number the Royal Malaysian Customs Department (RMCD) issues to businesses registered for Sales Tax or Service Tax.
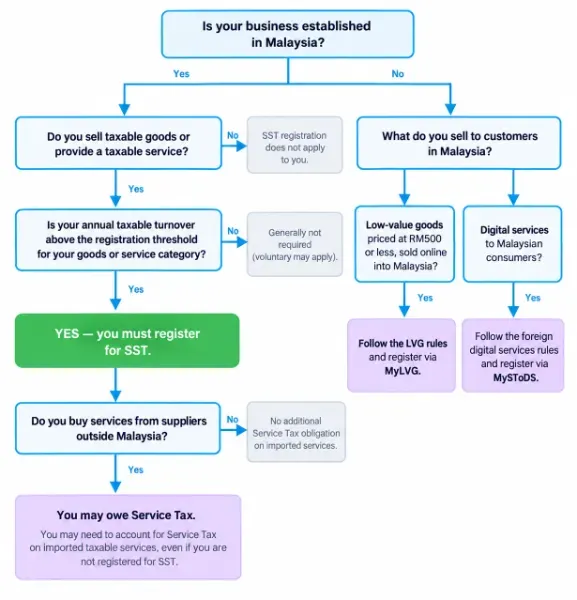
- SST obligations depend on what your business sells, where it is established, and whether it exceeds the applicable threshold. Separate rules apply to LVG sellers and foreign digital service providers.
- Common Sales Tax rates are 5% and 10%, although specific rates and exemptions apply. Service Tax is generally 6% or 8%, depending on the service, with specific rates for some services.
- Registered businesses must issue correct invoices, file returns, pay SST on time, and keep records that support their tax returns.
What is SST in Malaysia?
SST, or Sales and Service Tax, is an indirect consumption tax imposed on taxable goods and services in Malaysia.
In this context, indirect tax means SST is collected and accounted for at specific points, depending on whether Sales Tax or Service Tax applies.
The RMCD assigns an SST registration number to businesses or persons registered under the relevant SST regime. The RMCD can impose this consumption tax on taxable goods when registered manufacturers manufacture and sell them in Malaysia. Businesses that provide prescribed taxable services may need to register for and account for Service Tax once they meet the applicable requirements.
There are two major types of SST:
- Sales Tax, a single-stage tax imposed on certain goods manufactured locally or imported into Malaysia for domestic consumption.
- Service Tax applies to prescribed taxable services supplied in Malaysia and to certain imported taxable services.
SST was introduced on 1 September 2018 to replace the former Goods and Services Tax (GST) system.
Unlike GST, Sales Tax is generally imposed at a single stage, while Service Tax applies to prescribed taxable services. Meaning it’s imposed at a specific point in the supply chain, and this depends on the nature of the transaction.
Learn more: Customs Duty vs Sales & Service Tax in Malaysia
What Are the SST Registration Requirements?
Here’s a quick walkthrough of the major requirements for SST registration:
Sales Tax Registration Requirements
- Manufacturers must register for Sales Tax if the sales value of taxable goods exceeds RM500,000 over 12 months.
- Manufacturers must also register if they carry out sub-contract work on taxable goods and the value of that work exceeds RM500,000 over 12 months.
- Manufacturers below the threshold can apply for voluntary registration.
Service Tax Registration Requirements
Here is a breakdown of service tax registration requirements. Thresholds are measured over any 12-month period:
| Groups | Services | Registration Requirements | Current rates |
| A | Accommodations | RM500,000 | 8% |
| B | Food and Beverages | RM1,500,000 | 6% |
| C | Nightclubs, Dance Halls, Health Centers, Massage Parlours, Public Houses, Beer Houses, and Karaoke Centers | RM500,000 | 8% |
| D | Private Clubs | RM500,000 | 8% |
| E | Golf Club & Golf Driving Range | RM500,000 | 8% |
| F | Betting and Gaming | RM500,000 | 8% |
| G | Advocate & Solicitor, Syarie Lawyer, Public Accountant, Professional Engineer, Architect, Consultant, Management, Employment Agency, Private Agency (Guards/Protection), IT Providers, Online Platforms, Maintenance and Repair, Licensed/Registered Surveyor, Appraisers & Estate Agents | RM500,000 | 8% |
| H | Credit Card/Charge Card | No threshold | RM25 per principal or supplementary card and each subsequent year or part thereof |
| I | Insurance & Takaful | RM500,000 | 8% |
| I | Telecommunication | RM500,000 | 6% |
| I | Paid TV Broadcasting | RM500,000 | 8% |
| I | Parking Spaces Operators | RM500,000 | 6% |
| I | Automotive Repair Center | RM500,000 | 8% |
| I | Hire and Drive, Advertising | RM500,000 | 8% |
| I | Electricity | RM500,000 | 8% |
| I | Air Transport | RM500,000 | 8% |
| I | Cleaning | RM500,000 | 8% |
| I | Brokerage or Underwriting | RM500,000 | 8% |
| J | Logistics, Courier, and E-commerce Logistics | RM500,000 |
6% |
| J | Forwarding Agents | No threshold | 6% |
Source: Royal Malaysian Customs Department, registration thresholds and Service Tax (Rate of Tax) (Amendment) Order 2024. Correct as of 14 September 2026.
Service Tax Registration Requirements (Expansion)
| Services | Registration Requirements | Current Rate |
| Financial services | RM1,000,000 in taxable services within a 12-month period | 8% |
| Private healthcare, traditional and complementary medicine, and allied health services | RM1,500,000 in taxable services over 12 months | 6% |
| Rental or leasing services | RM1,000,000 in taxable services over 12 months | 6% |
| Construction work services | RM1,500,000 over 12 months | 6% |
| Private school education | More than RM60,000 in fees per student per academic year | 6% |
| Higher education institutions | RM500,000 in taxable services over 12 months | 6% |
Source: Royal Malaysian Customs Department and Ministry of Finance. Correct as of 14 September 2026.
MSMEs are exempt from service tax on rental and leasing altogether, rather than paying a reduced rate. To qualify, annual sales must not exceed RM1,500,000 and paid-up ordinary share capital must not exceed RM2,500,000. Tenants claim it by declaring MSME status through RMCD’s MyPMK system. Businesses with annual sales under RM1,000,000 have been exempt since 1 July 2025; the RM1,000,000 to RM1,500,000 band has been exempt since 1 January 2026.
Do I Need to Register?
Here’s what SMEs need to know about SST registration:
- You must register if the value of your taxable goods or services exceeds the applicable registration threshold within a 12-month period.
- SMEs generally must register for Sales Tax when the sales value of taxable goods exceeds RM500,000 over a 12-month period.
- Service Tax registration thresholds vary by service category, with most ranging from RM500,000 to RM1.5 million in taxable services over a 12-month period.
- SMEs that do not meet the registration threshold are not required to register for SST, but eligible businesses may apply for voluntary registration.
- The threshold depends on your taxable turnover, not your business’s total turnover from all revenue sources.
Note:
|
If you are unsure whether your business needs to register for SST, check the tables above to identify the requirements that apply to your taxable goods or services.
How SST Applies to Foreign Businesses
Foreign businesses may have different SST obligations without a physical presence in Malaysia. Obligations depend on whether the business sells low-value goods, offers digital services to Malaysian consumers, or supplies taxable services to Malaysian businesses.
SST Obligations for Foreign Sellers of Low-Value Goods
Low-Value Goods (LVG) sold for RM500 or less, brought into Malaysia by land, sea, or air, and sold online by a seller located either in or outside Malaysia.
Malaysia has imposed a 10% sales tax on LVG, excluding cigarettes, tobacco products, intoxicating liquors, and smoking pipes. Foreign sellers are obligated to register for LVG Sales Tax when the total value of imported LVG exceeds RM500,000 within a 12-month period.
After registration, the seller charges 10% Sales Tax on the sale value of the LVG. The taxable sale value doesn’t include taxes, duties, or charges like transportation and insurance. Registered LVG sellers file the LVG-02 return every three months and pay the sales tax due for that taxable period.
SST Obligations for Foreign Businesses Providing Digital Services
Digital service means any service delivered or subscribed to over the internet or another electronic network that cannot be obtained without information technology and whose delivery is essentially automated.
Malaysia has imposed an 8% service tax on qualifying digital services since 1 March 2024. The service tax is charged and levied on any foreign digital service provider that provides qualifying services to Malaysian consumers.
A foreign service provider must register when the total value of digital services supplied to Malaysian consumers exceeds RM500,000 over a 12-month period. After registration, the foreign service provider must charge 8% service tax on qualifying digital services supplied to Malaysian consumers.
SST Obligations for Imported Services Used By Malaysian Businesses
If you buy a taxable service from a supplier outside Malaysia, you may have to account for the service tax yourself. The obligation sits with the Malaysian business receiving the service, not with the overseas supplier, and it applies whether or not you’re registered for service tax.
The tax becomes due when you pay the invoice or receive it, whichever comes first.
How you declare it depends on your registration status. If you’re registered, include it in your usual SST-02 return for that taxable period. If you’re not registered, you declare and pay using form SST-02A through the MySST portal.
The rate follows the type of service you’ve bought. Please refer to the table above.
Learn more: Malaysia import tax in 2026: duties, SST, and how to calculate them
How to Register SST in Malaysia
Here’s a walkthrough of how to register for SST in Malaysia:
- To get started with SST registration, visit Malaysia’s MySST portal. Certain foreign businesses register through separate registration systems. Qualifying LVG sellers register through MyLVG, while foreign digital-service providers use MySToDS.
- Complete the relevant online registration application and provide the requested business and taxable-activity information.
- RMCD will email you a notification after your registration is successful.
- You’ll receive the relevant SST registration details/number.
- You’ll also receive details such as the effective date of registration and the rules and responsibilities you need to acknowledge.
What Goods Are Taxable Under Sales Tax in Malaysia?
Sales tax applies to goods manufactured in Malaysia and to goods imported into Malaysia. What you pay depends on how the goods are classified, not on what they’re called.
| Rate | What it applies to | Examples |
|---|---|---|
| Exempt | Essential goods listed in the Sales Tax (Goods Exempted from Sales Tax) Order 2025 | Rice, chicken, beef, vegetables, imported apples, oranges, mandarin oranges and dates, cooking oil, medicines, books and newspapers, basic construction materials, agricultural inputs |
| 5% | Non-essential and discretionary goods specifically listed in the Sales Tax (Rate of Sales Tax) Order 2025 | King crab, salmon, cod, essential oils, silk fabrics |
| 10% | The default rate. Any taxable good that is neither exempted nor listed at 5% falls here | Racing bicycles, antique hand-painted paintings, and every taxable good not listed elsewhere |
| Specific rates | Charged per unit rather than as a percentage. Limited to certain classes of petroleum, mainly refined petroleum | Refined petroleum products |
Source: Royal Malaysian Customs Department, Sales Tax (Rate of Sales Tax) Order 2025 and Sales Tax (Goods Exempted from Sales Tax) Order 2025. Correct as of 14 September 2026.
If you’re unsure which band your goods fall into, use the tariff classification as the deciding factor, not the product description. Confirm it against the current orders or ask RMCD’s Technical Services Division before you price anything.
SST Exemptions
Here’s a breakdown of SST exemptions:
- Many essential goods are exempt from Sales Tax, including rice, chicken, beef, certain fish, vegetables, cooking oil, medicine, books/newspapers, and basic construction materials. Agricultural inputs, such as fertilizers, pesticides, and machinery.
- Exemptions for certain people: Government departments, local authorities, duty-free shops, and other approved people are exempted from sales tax on qualifying purchases or imports.
- Manufacturing exemptions: Eligible manufacturers can obtain exemptions on raw materials, aids, and components used in manufacturing.
- Eligibility may depend on the buyer, the type of goods, the intended use, and the conditions in the relevant exemption order.
- Some Sales Tax exemptions require businesses to apply for an exemption certificate or approval through MySST, depending on the applicable exemption category and conditions.
To avoid noncompliance risks, businesses should stay up to date on changes to SST requirements, verify eligibility criteria, and confirm the tariff classification and applicable SST treatment
What Are the Penalties for Late SST Payments?
Late SST payments can result in financial penalties. According to MySST, late SST payments incur:
- 10% of the tax amount for the first 30 days
- An additional 15% for the second 30-day period on the outstanding balance
- An additional 15% for the third 30-day period, based on the outstanding balance.
- The maximum rate is a 40% penalty after a period of 90 days
What are the SST Invoicing Requirements?
When to Issue An Invoice
A registered manufacturer must issue invoices in Bahasa Melayu or English when selling taxable goods. For service tax purposes, persons registered for Service Tax must also issue invoices in Bahasa Melayu or English. These invoices can either be electronic or hard copy.
What Should a Service Tax Invoice Include?
The invoice for service tax should include:
- The serial number
- Invoice date
- Registered person’s name
- Address and identification number
- Description of the taxable service
- Discounts
- Amount before tax
- Total amount including tax
- Applicable service tax rate and tax charged separately
- If an amount is shown in a currency other than MYR, the invoice must also show the amount in MYR using the applicable selling exchange rate.
How to File an SST-02 Return
Registered manufacturers and registered service providers generally file the SST-02 return every two months.
You must submit the return electronically through MySST by the last day of the month following the taxable period, even if no tax is payable.
The filing process is largely the same for Sales Tax and Service Tax. The main difference is what they report: registered manufacturers use SST-02 to declare Sales Tax, while registered service providers use it to declare Service Tax.
Manage Cross-Border Payments With WorldFirst
Understanding SST and how it affects your business is one part of doing business in Malaysia. You also need a reliable platform to collect payments, pay overseas suppliers when importing goods, and manage multiple currencies.
The World Account collects business payments in 20+ currencies. With this account, you can also collect from supported marketplaces and payment gateways and send payments internationally in multiple currencies.
If your business also sources from China, you can use WorldFirst to pay your 1688.com suppliers from Malaysia with ease.
Open a World Account for free to manage your cross-border payments in one place.
FAQs about SST in Malaysia
1. What is an SST registration number in Malaysia?
An SST registration number is the identification number issued to a business after it registers for Sales and Service Tax in Malaysia. The Royal Malaysian Customs Department (RMCD) issues the number as part of the registration process.
2. What is the SST registration threshold in Malaysia?
Manufacturers generally must register for Sales Tax when the sales value of taxable goods exceeds RM500,000 over a 12-month period. Service Tax thresholds vary by taxable service category, so businesses need to check the registration limit that applies to their specific services.
3. Do foreign companies need to register for SST in Malaysia?
Foreign companies must register for SST when they meet the requirements of a regime that applies to overseas businesses. This can include foreign sellers of low-value goods and foreign digital-service providers that exceed the relevant RM500,000 registration threshold.
4. Are services purchased from overseas suppliers subject to SST?
Taxable services purchased from overseas suppliers can be subject to Service Tax in Malaysia. Malaysian businesses that acquire imported taxable services may need to account for and pay Service Tax, depending on the service type and the applicable SST rules.
Sources
- https://mysst.customs.gov.my/registering-business/
- https://mysst.customs.gov.my/faq-expansion-of-service-tax-scope-2025/
- https://www.mof.gov.my/portal/en/news/press-release/revision-to-the-expanded-sales-tax-and-service-tax-take-into-account-public-and-industry-feedback
- https://mysst.customs.gov.my/wp-content/uploads/2025/03/Service-Tax-Rate-Of-Tax-Order-2018.pdf
- https://mysst.customs.gov.my/wp-content/uploads/2025/03/PERINTAH-CUKAI-PERKHIDMATAN-KADAR-CUKAI-PINDAAN-2024.pdf
- https://pub-359af8e1f79c472292a7e44ec60f3027.r2.dev/Service%20Tax%20Policy/EN/STP%202-2025%20(Rental%20or%20Leasing)%20(Amnd%20No.5)%20220726.pdf
- https://mysst.customs.gov.my/faq-services-tax/
- https://mysst.customs.gov.my/faq-sales-tax/
- https://mysst.customs.gov.my/faq-transition-of-sales-tax-rate-changes-2025/
- https://mysst.customs.gov.my/sst-orders/
- https://www.mof.gov.my/portal/en/news/press-release/targeted-revision-of-sales-tax-rate-and-expansion-of-service-tax-scope-effective-1-july-2025
- https://mysst.customs.gov.my/wp-content/uploads/2025/02/Information-about-Imported-Taxable-Services.pdf
- https://mystods.customs.gov.my/storage/app/media/pdf/guide/guide-on-transitional-rules-for-the-change-in-st-rate-to-8-on-digital-service-provided-by-frp.pdf
- https://mystods.customs.gov.my/storage/app/media/pdf/legislation/7-pua-67-2024-service-tax-rate-of-digital-services-taxamendment-2024.pdf
- https://mysst.customs.gov.my/background/
- https://mysst.customs.gov.my/understanding-sst/
- https://mysst.customs.gov.my/filing-text-returns/
- https://mysst.customs.gov.my/issuing-invoices/
- https://mysst.customs.gov.my/penalties/
- https://mylvg.customs.gov.my/FAQ
- https://mystods.customs.gov.my/index.php/about-mystods
- https://www.worldfirst.com/my/product/collect/
- https://www.worldfirst.com/my/pricing/
- https://www.worldfirst.com/my/product/pay/1688-world-pay/